The best investing app is the one that fits how you actually invest, not the one that tops a ranking. An app that suits a hands-off index fund investor will frustrate an active trader, and the reverse is also true. The honest answer to "which is best" is a match between fees, features, and your own behavior.
The word itself carries a warning. According to Merriam-Webster, "best" can mean offering or producing the greatest advantage, utility, or satisfaction — and advantage is measured against a purpose. An app is a tool. Judging a tool without naming the job it must do is how investors end up paying for features they never use, or missing ones they need.
This guide does not name winners. Instead, it breaks down the categories of fees, the features that matter, and the fit questions that decide the choice. You can apply the framework to any app on your shortlist.
What Should You Actually Compare Before Choosing an App?
Start with four things: what the app charges, what it lets you buy, how it handles taxes and account types, and what it does when you stop paying attention. Most comparisons lead with interface design. That matters less than it looks. A beautiful app that charges more, or nudges you into frequent trading, costs you money for years.
A useful discipline is to write your own criteria before you open a single product page. Decide whether you are a buy-and-hold investor or an active trader, whether you want automated contributions, and which account types you need. Then score each app against your list. This is the same methodical order used in fund comparisons: criteria first, comparison second.
How Do App Fees Work, and Where Do They Hide?
Fees on investing apps come in several shapes, and not all of them appear on the pricing page as a line called "fee."
- Commissions. A charge per trade. Zero is not always zero across every asset type, so check the schedule for the specific securities you plan to buy.
- Spreads and markups. For some assets, the app's revenue comes from the difference between the price you pay and the price the app obtained. This cost is embedded in the trade price rather than billed separately, which makes it easy to miss.
- Subscription tiers. Some apps charge a monthly fee for research tools, extended trading hours, or larger instant deposits. Paying for features you do not use is pure drag.
- Fund-level costs. If you buy funds through the app, the funds carry their own expense ratios. The app's fee schedule and the fund's costs are separate layers, and both compound.
- Custody and inactivity charges. Less common at mainstream retail apps now, but worth confirming, especially for accounts you plan to leave alone for long stretches.
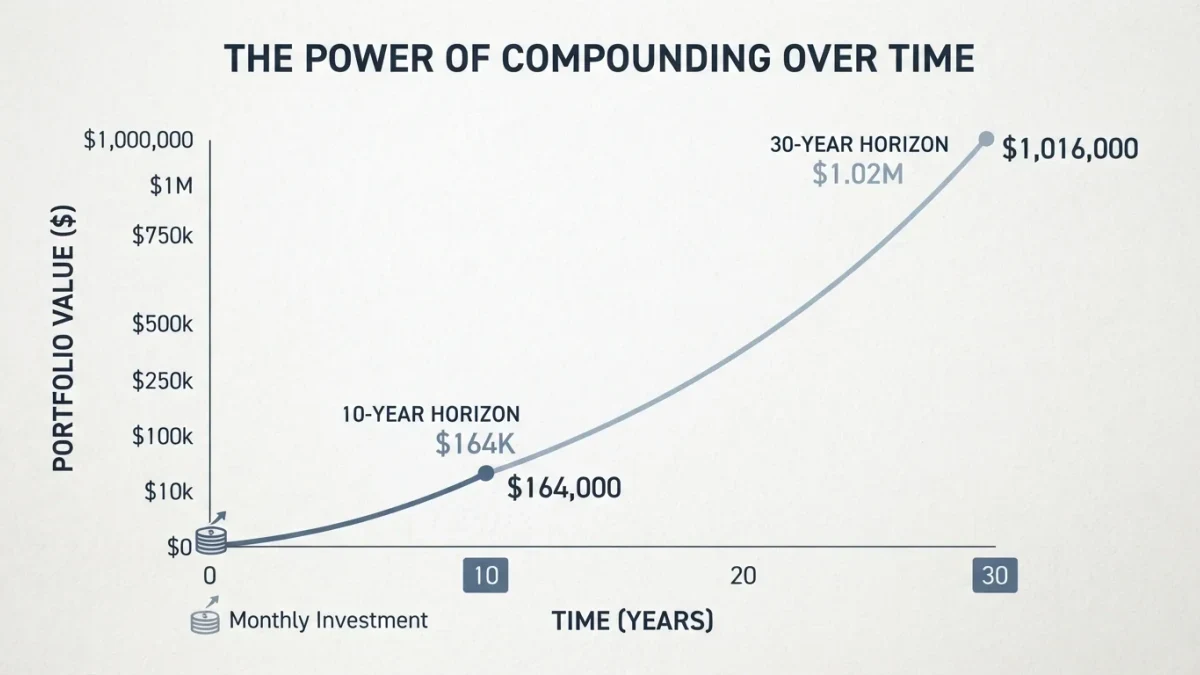
The compounding point deserves emphasis. A small recurring cost is not small over decades, because every dollar paid in fees is a dollar that never compounds. Our breakdown of what a 1% fund fee costs over thirty years shows the arithmetic in detail. When you compare apps, compare the total cost of ownership: app fees plus the costs of the assets you would actually hold through each app.
Which Features Matter, and Which Are Noise?
Features divide into two groups: ones that change outcomes, and ones that change how the app feels.
Outcome-relevant features include automated recurring investments, dividend reinvestment, fractional shares, retirement account support, clean tax documents, and the ability to transfer your holdings out without penalty. Each of these either saves you money, saves you time, or protects optionality. Fractional shares and recurring buys matter most for investors starting small; our guide on how to start investing with little money explains why consistency beats size early on.
Feel-oriented features include price alerts, social feeds, confetti animations, and gamified streaks. These are not automatically bad, but they are designed to increase engagement, and engagement is not the same as better results. Our article on how often you should check your portfolio covers this question. If an app's design pushes you toward more frequent action, treat that as a cost, not a feature. For related coverage, see Dollar-Cost Averaging vs Lump Sum: What the Evidence Says.
Research tools sit between the two groups. For a long-term investor, a clear prospectus and a fund's holdings list are enough; our guide on reading a fund prospectus in twenty minutes shows what to look for. Advanced charting matters mainly to active traders.
Which App Fits Your Experience Level?
Match the app's complexity to your process, not your ambitions.
- Beginners and hands-off investors. Prioritize low total cost, fractional shares, automatic recurring buys into broad funds, and simple tax reporting. You need very little else. Every extra feature is a potential distraction.
- Intermediate investors building a portfolio. Add retirement account options, transfer flexibility, and decent fund screening. At this stage, account-type decisions start to matter for taxes, so an app that supports the accounts you need saves future friction. Our comparison of the Roth IRA versus the traditional IRA is the decision those features serve.
- Active traders. Execution quality, order types, and real-time data become the priority. Be honest about whether you are actually in this group. The evidence on dollar-cost averaging versus lump sum is a reminder that simple, repeated processes are hard to beat.
A practical test: imagine using the app during a sharp market drop. If your likely response would be to sell everything because the app made selling feel effortless, choose an app whose design adds friction to impulsive trades and makes automatic contributions the default.
What This Means for Your Choice
Our analysis reduces the decision to three checks. First, price out the total cost of what you would actually hold through the app, not just the headline commission. Second, confirm the features tied to outcomes you care about: recurring buys, reinvestment, account types, and clean exits. Third, judge the app's design honestly — does it support your process or fight it?
One more check that comparisons often skip: how hard is it to leave? An app that holds your assets should let you transfer them out in kind, without selling positions or charging a punitive exit fee. Lock-in is a cost that only shows up when you try to leave, which is exactly when it hurts most.
None of this is investment advice, and no app changes what a sound portfolio requires: broad diversification, low costs, and behavior you can sustain. The app is plumbing. The plan is the asset. If you are still shaping the plan itself, our investing section collects the guides on costs, compounding, and portfolio construction in one place, and our look at what compounding actually does in an index fund is a good place to see why the plumbing matters less than time in the market.