An investing calculator turns four inputs — how much you put in, how often, the return you assume, and how long you wait — into one projected balance. It does this by applying compound-growth math, where each period's gain is calculated on a base that includes earlier gains. The most important qualification is that the return input is an assumption, not a promise; the output is only as honest as the number you feed it.
Merriam-Webster defines use as "to put into action or service," and that is the right frame for these tools: a calculator is a service you put to work on a specific question, not an oracle. Ask it a narrow question — what happens to a fixed monthly contribution over a fixed period at a stated assumed rate — and it answers precisely. Ask it to predict markets and it fails quietly.
This guide walks through the mechanism the calculator runs, a worked hypothetical with every assumption stated, and the inputs where people most often fool themselves. It is education, not investment advice, and no projection here describes any particular fund or portfolio.
What math does an investing calculator actually run?
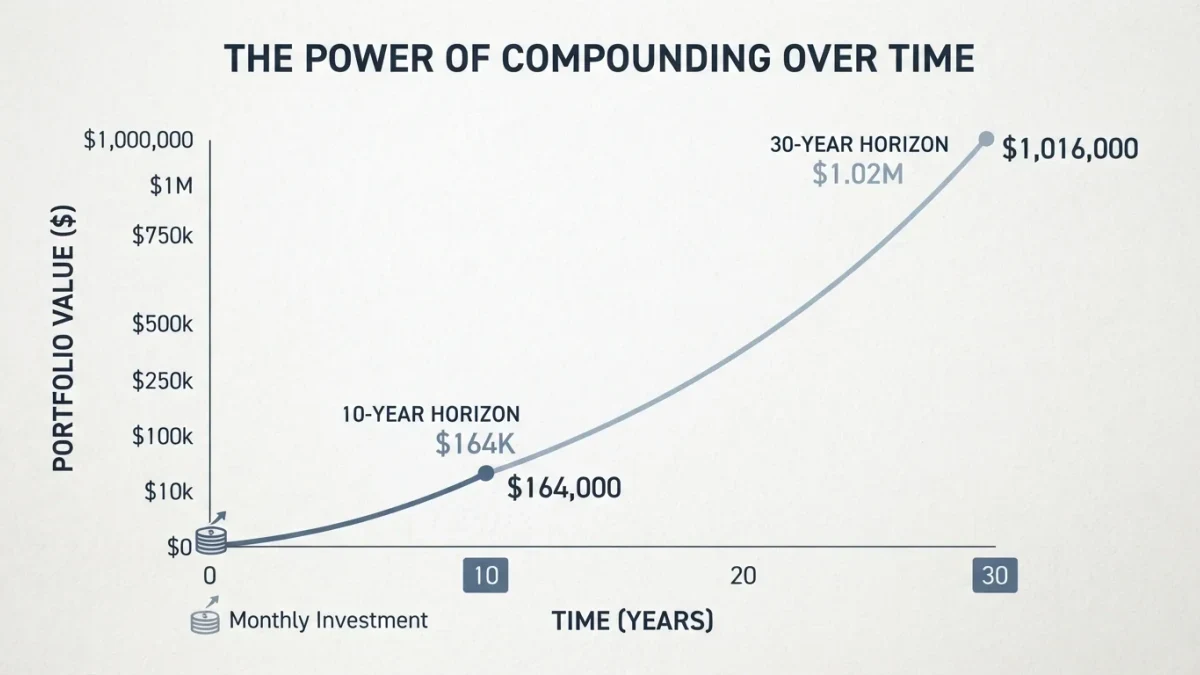
Most retirement and goal calculators run a future-value formula. Each contribution grows at the assumed rate, compounded at a stated interval, and the results stack. The mechanism matters because it explains the calculator's two most striking behaviors: early years barely move the balance, and late years move it dramatically.
That shape is not a quirk of the software. It is what compounding does. Gains earned early get reinvested and earn gains of their own, so the growth base widens every period. Readers who want the same mechanism traced through an actual fund can see it in What Compounding Actually Looks Like in an Index Fund.
The flip side of the mechanism is that it works on costs as well as gains. The same compounding math that grows a balance also grows a fee's drag, which is why the calculator is worth running twice — once with your return, once with the return minus fees.
What does a worked example look like, with assumptions stated?
The following is a hypothetical illustration, not a projection of any real investment. Assumptions: $200 contributed every month, a 7% annual return compounded monthly, no taxes, no fees, and no changes to the contribution for 30 years.
Running the future-value formula on those inputs produces a balance of roughly $244,000, of which about $72,000 is the money you contributed and the rest is assumed growth. Adjust the assumptions and the output moves: the same $200 a month over 20 years at the same assumed rate lands far lower, because the final decade — where the growth base is widest — never happens.
What this means in practice: the calculator's most useful output is often not the final number but the gap between contributions and balance. That gap is the part of the plan that depends on an assumed return rather than on your own deposits, and it is the part that deserves the most skepticism.
Which inputs cause the most mistakes?
Three inputs do most of the damage.
- Assumed return. A single fixed rate hides the fact that real returns arrive unevenly. A long-horizon plan should be tested at more than one rate, including a deliberately low one, rather than anchored to one optimistic figure.
- Fees. A calculator that ignores expense ratios overstates the outcome. The difference between a 7% and a 6% assumed return on the hypothetical above is on the order of tens of thousands of dollars over 30 years — the same arithmetic behind What a 1% Fund Fee Costs Over Thirty Years.
- Contribution growth. Most people raise their contributions over a career. A calculator that assumes a flat $200 for three decades understates what a plan with annual increases would accumulate — and, less obviously, it can understate the required discipline too.
Inflation is a fourth, quieter issue. A nominal balance of $244,000 in 30 years buys less than $244,000 does today. If the calculator offers an inflation-adjusted output, use it; if not, run the same inputs at a lower rate to approximate a real-return view.
How should you turn a projection into a goal?
A calculator answers "what does this plan produce?" Goal planning runs the question in reverse: "what plan produces this target?" The practical steps:
- Write the target as an amount and a date, in today's purchasing power.
- Choose a conservative assumed real return, and state it in writing next to the result.
- Solve for the required monthly contribution, not the other way around.
- Re-run the numbers at a lower rate. If the gap between outcomes is unaffordable, the plan depends too heavily on the assumption.
- Repeat the exercise on a fixed schedule — yearly is common — rather than after every market move.
That last step deserves emphasis. A calculator is a planning tool, and rerunning it daily converts a plan into a mood tracker. The case for checking on a calendar rather than a screen is laid out in How Often Should You Check Your Portfolio.
For the contribution side of the plan, the choice between investing a lump sum and spreading it over time changes the input, not the math. The evidence on that trade-off is summarized in Dollar-Cost Averaging vs Lump Sum: What the Evidence Says.
What are the limits of any investing calculator?
The limits are structural, and naming them plainly is the point of running the tool at all. A future-value calculator assumes a smooth return; markets do not deliver smooth returns. It assumes contributions arrive on schedule; jobs, expenses, and emergencies interrupt. It assumes you stay invested through drawdowns, which is a behavioral assumption about you, not a mathematical one about money.
Sequence matters too. Two portfolios with the same average return can end at different balances depending on when the strong and weak years arrived relative to your contributions and withdrawals. A single-rate calculator cannot see that. For long-horizon savers still contributing, this cuts in their favor more often than not — buying through downturns — but the tool will not show it either way.
The house view here is quiet skepticism: use the calculator to bound the problem, not to pick the answer. If a plan only works at an optimistic rate, it is not yet a plan.
Practical takeaways
An investing calculator is a way of putting compound-growth arithmetic into service on your own numbers, and its value comes from disciplined inputs. State the assumed return, subtract fees, adjust for inflation where you can, and test at least one pessimistic case. Treat the gap between what you contribute and what the projection shows as the fragile part of the plan. And remember what the evidence established and what it did not: the arithmetic is certain, the return is not, and the contribution you control is the most reliable input on the screen.